
Simple Checkbook Ledger
- Rating
- 3.4
- Downloads
- 100.00K
- Content Rating
- Everyone
Simple Checkbook Ledger - Screenshots
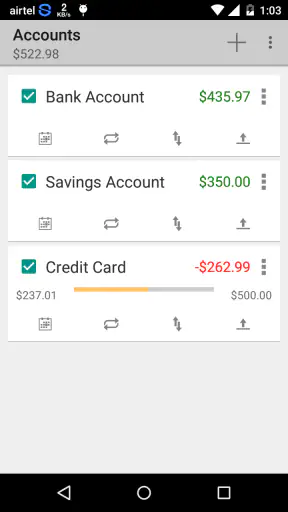
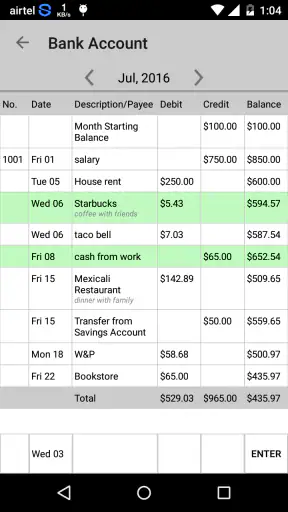
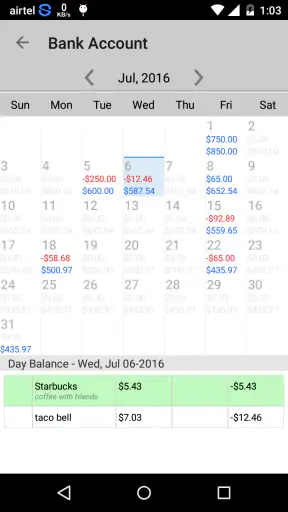
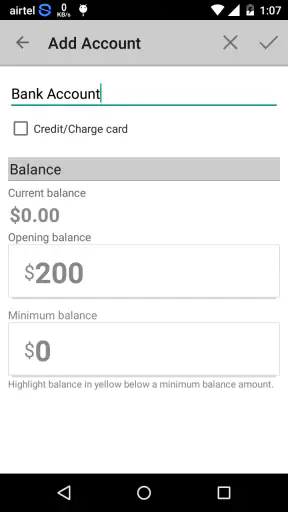
Pros
- Simple
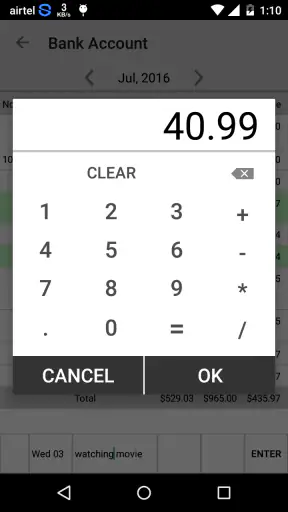
- uncluttered interface makes entries quick to record.
- Supports multiple accounts for separating personal finances.
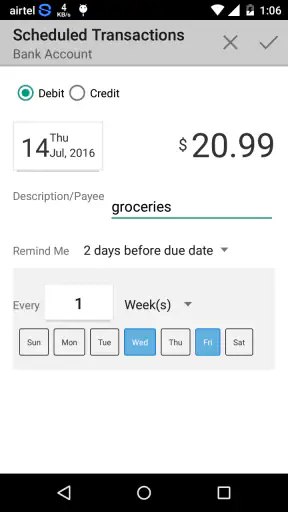
- Recurring transactions reduce repetitive manual entry.
- Clear balance history helps track spending over time.
- Useful offline access without requiring a constant internet connection.
Cons
- Limited budgeting and financial planning tools for advanced users.
- May lack automatic bank syncing and transaction importing.
- Manual categorization can become time-consuming with many entries.
- Reports and charts may be too basic for detailed analysis.
- Backup and device-transfer options may require extra attention.
Simple Checkbook Ledger - Description
- App Name
- Simple Checkbook Ledger
- Package Name
- com.apps.teelu.simplecheckbookledger
- Developer
- Teelu Apps
- Category
- Finance
- Last Updated
- Aug 3, 2016
- Version
- 3.5
I approached Simple Checkbook Ledger as a practical money-management tool rather than a full banking replacement. It is a free finance app from Teelu Apps, built around the familiar idea of writing down income, spending, and account activity in one place. That narrow focus is also its main appeal: if you want a personal ledger that feels closer to a digital checkbook than a complicated budgeting platform, it is easy to understand.
My recommendation depends on what you expect from a finance app. For recording transactions manually and keeping a running view of an account, it can be useful. For automatic bank connections, shared household budgeting, investment tracking, or detailed financial planning, I would look elsewhere. The important question is not whether it has the longest feature list, but whether its straightforward approach matches the way you already handle money.
Simple Checkbook Ledger as a decision guide
Start with the kind of money tracking you actually need
The best reason to choose this app is that you want to enter transactions yourself. That may sound basic, but manual entry gives you a deliberate moment to notice where money is going. I found that this style suits people who prefer control over automation, especially when they want a simple record for a checking account, cash spending, or a small personal fund.
The app’s store summary describes it as a way to manage accounts with ease, while its short description presents it as a simple checkbook ledger. Those descriptions set the right expectation. This is not the sort of finance tool I would open expecting a broad financial dashboard. I would open it to record a deposit, add a purchase, check the balance, and keep the account history tidy.
That distinction matters when comparing categories. A banking app usually shows transactions imported from a financial institution, while a budgeting app may organize spending into categories and targets. A checkbook ledger takes a more direct route: you maintain the record. That can be a weakness if you dislike data entry, but it can also be a strength when you need a private, uncomplicated running balance.
What I would check before committing
Before moving your regular money tracking into it, I would decide how many accounts you need to follow and how often you are willing to update them. Someone who checks one account and records purchases immediately may find the routine comfortable. Someone with several cards, loans, savings accounts, and irregular income may quickly outgrow the ledger format.
I would also consider whether you need your financial information to appear automatically. Manual ledgers are only as accurate as the last entry. If you forget a purchase or enter the wrong amount, the balance can drift away from reality. That is not a flaw unique to this app; it is the trade-off built into this entire category of tools.
The app is free to use, with in-app purchases priced at $1.99 per item. That makes it easy to try without making an immediate financial commitment. It is rated for Everyone, so its presentation is accessible rather than aimed at a specialist audience. The current version is 3.5, and it requires iOS 11 or later, which is worth checking before installing it on an older device.
Where the simple ledger approach works best
I see three particularly sensible uses. The first is personal checking-account control: enter deposits and purchases as they happen, then use the ledger to anticipate the balance before a bill clears. The second is cash management, where there is no bank feed to import. The third is a small shared-purpose account, such as a household envelope or a side project, provided everyone agrees on who records each transaction.
A useful habit is to record pending commitments separately in your own routine, even if you do not yet treat them as completed transactions. For example, after scheduling a bill, I would make a note of it and then reconcile the ledger when the payment actually leaves the account. This reduces the chance of spending money that is technically still visible in the balance but already promised elsewhere.
Where it wins over more elaborate finance apps
The biggest advantage is mental simplicity. Many modern finance apps try to become a complete financial command center. That can be helpful, but it also means more screens, more categories, and more decisions before a basic transaction is recorded. A checkbook-style ledger keeps the central task obvious.
I also like the accountability of manual recording. When a purchase is imported automatically, it can disappear into a list that I never really review. Entering it myself makes me pause and label the event in plain language. For people trying to reduce casual spending, that small amount of friction can be more useful than an attractive chart.
Another advantage is that the format can work for accounts that do not cooperate with financial aggregation. A cash balance, a local account, or a temporary fund can be tracked in the same general manner as a checking account. I would not treat that as a substitute for official records, but it is a practical personal reference.
Three habits that make the app more dependable
First, reconcile at a fixed moment instead of waiting for confusion. I would choose a regular point in the week to compare the ledger with the account balance and correct missed entries while they are still easy to remember. A short, consistent review is safer than trying to reconstruct an entire month after several forgotten purchases.
Second, use a clear naming pattern for transactions. Generic notes such as “purchase” are not helpful later. I would identify the shop, purpose, or bill in a way that makes the history searchable to my own memory. This turns the ledger from a balance counter into a useful record when I need to understand an unexpected change.
Third, separate timing from spending decisions. A transaction can be financially important even when it has not cleared yet. I would keep a personal list of upcoming payments and use the ledger for confirmed activity, then review both before making a large purchase. This avoids treating the visible balance as spendable money by default.
A realistic everyday routine
Imagine I receive income, pay a utility bill, buy groceries, and use cash for a few small purchases during the week. I would enter the income first, record the bill when it leaves the account, and add each purchase as soon as possible. At the weekend, I would compare the running total with the bank’s balance and look for anything missing.
The value here is not a sophisticated forecast. It is the ability to answer a simple question without opening several services: “What should be left in this account after the transactions I know about?” If I also have a scheduled payment, I would account for it in my planning before assuming the displayed balance is freely available.
This routine is especially suitable for someone who has tried automatic budgeting but stopped checking it. A smaller system that becomes part of a daily habit can be more effective than a powerful system that feels like administrative work.
Where alternatives may fit better
I would choose a bank’s own app when the priority is official, up-to-date account information, transfers, deposit tools, or alerts tied directly to the institution. A manual ledger can complement a banking app, but it should not be treated as the authoritative source for available funds.
I would choose a broader budgeting service when I needed spending categories, monthly limits, shared planning, recurring financial goals, or automatic transaction collection. Those tools are usually better for answering questions such as how much I spend on dining over time or whether a household is staying within a planned budget. Simple Checkbook Ledger is more focused on recording activity than analyzing an entire financial life.
I would also look at a spreadsheet when I wanted custom formulas, long-term reports, or a format designed around unusual income. A spreadsheet takes more effort to build and maintain, but it can be shaped around a business, freelance work, or detailed cash-flow planning. This app makes more sense when I want a ready-made ledger rather than a blank system to design myself.
Limitations I would take seriously
Manual entry is the central limitation. If you regularly forget to record transactions, the app can give you a false sense of precision. The cleanest ledger is not necessarily the most accurate one; accuracy comes from consistent reconciliation. I would not rely on it alone when making a high-stakes payment decision.
The narrow scope may also feel restrictive to people who want financial analysis. If your main goal is to discover patterns, plan debt reduction, or monitor several financial products together, a simple transaction history will not answer every question. You may end up copying information into another tool, which removes some of the convenience.
There is also a personal workflow issue. Some users enjoy entering each transaction, while others experience it as repetitive bookkeeping. No interface can completely remove that difference. I would test the routine for several days before moving all account tracking into it. If recording a purchase already feels like a chore, the habit is unlikely to survive a busy month.
What the audience and track record suggest
The app has passed the 100K-plus install mark and carries an average rating of 3.4 from around 2.5 thousand ratings, with roughly 1.2 thousand written reviews. I read that as a mixed but meaningful signal: enough people have found the basic idea useful, while the middling average suggests that the simple approach will not satisfy everyone.
Its release date of August 3, 2016, also helps frame the experience. This is an established ledger concept, not a newly invented approach. That can be reassuring if you want something familiar, but it also means I would not choose it expecting the same breadth or polish associated with newer all-in-one financial platforms.
Teelu Apps has kept the product at version 3.5, giving it a clear identity as a focused finance utility. I would judge it by whether the core ledger routine works for me, not by expecting it to compete feature for feature with banking ecosystems or full budgeting suites.
The cost of switching from another method
Moving from paper is relatively easy because the mental model is similar. I would begin with the current balance, then enter only the transactions needed to make the running record useful. There is no advantage in spending an entire afternoon rebuilding years of history unless I specifically need that archive in the app.
Moving from a spreadsheet is more complicated because a spreadsheet may contain custom categories, formulas, or notes that do not translate neatly into a ledger workflow. Before switching, I would save a copy of the old file and decide whether I need historical detail or only a clean starting point. A staged change is safer than deleting the system that already works.
Moving from an automatic finance app may feel like a step backward at first. The benefit is more intentional control; the cost is remembering every entry. I would use both systems briefly, compare balances, and only then decide whether the manual routine is sustainable. That trial also reveals whether the app fits the way I actually spend rather than the way I imagine I spend.
Privacy-minded and low-complexity use
For someone who prefers not to connect every account to a financial service, a manually maintained ledger can feel more comfortable. It keeps the user in charge of what gets recorded, though I would still treat any finance app as sensitive and use normal device-security habits. The important distinction is that convenience comes from entering information yourself rather than from automatic account aggregation.
This makes the app a reasonable option for a person who wants a focused record without turning money management into a large project. It is also approachable for a family member who finds detailed budgeting software intimidating, as long as another person helps establish a reliable reconciliation routine.
My recommendation
I recommend Simple Checkbook Ledger to users who want a free, direct way to maintain a personal account record and who are willing to enter transactions consistently. Its strongest quality is not a long list of tools; it is the clarity of the basic ledger idea. The free entry point makes testing the workflow straightforward, while the Everyone rating keeps it approachable for ordinary household use.
I would skip it if automatic bank updates, advanced reports, shared budgeting, or a complete financial overview are essential. In those cases, a banking app, budgeting platform, or carefully built spreadsheet is likely to be a better match. Choosing this app means accepting manual responsibility in exchange for a simpler routine.
My final view is cautiously positive. I would install it for one uncomplicated account, use a regular reconciliation schedule, and keep the official banking app available for confirmation. If that arrangement reduces confusion and helps me notice spending, it is doing its job. If I repeatedly forget entries or need broader financial analysis, I would switch categories rather than force a checkbook ledger to become something it was never designed to be.
FAQ
What is Simple Checkbook Ledger used for?
Simple Checkbook Ledger is designed to help you record and monitor everyday financial transactions in a straightforward way. You can enter deposits, withdrawals, payments, and other adjustments, then use the running balance to understand how much money should be available. It is particularly useful for people who prefer manual control over their budget rather than automatic bank synchronization.
Does Simple Checkbook Ledger connect directly to my bank account?
The app is primarily intended for manual transaction tracking, so users should not assume that it automatically connects to their bank or imports transactions. This can be an advantage for privacy and simplicity, but it also means that you must enter purchases, deposits, fees, and corrections yourself. Always compare the ledger with your bank statement to identify missing or incorrectly recorded transactions.
Can I use Simple Checkbook Ledger for multiple accounts or purposes?
Simple Checkbook Ledger can be useful for organizing different financial records, depending on the version and features available on your device. Before downloading, check whether it supports the number of accounts, ledgers, or categories you need. Users managing checking, savings, cash, or shared household finances should also verify how easily separate balances can be maintained.
Is Simple Checkbook Ledger suitable for detailed budgeting?
The app is best understood as a checkbook and transaction ledger rather than a complete personal-finance platform. It can help you keep an accurate record of money coming in and going out, but it may not provide advanced tools such as automatic categorization, investment tracking, bill reminders, or long-term financial reports. It is a good choice for simple, hands-on money management.
Is my financial information safe when using Simple Checkbook Ledger?
Because you may enter sensitive information such as balances, transaction descriptions, and payment details, review the app’s privacy policy and requested permissions before using it. Avoid storing full card numbers, passwords, or unnecessary personal data in transaction notes. You should also check whether the app offers backups, exports, or device security options so your records remain protected if your phone is lost or replaced.


